
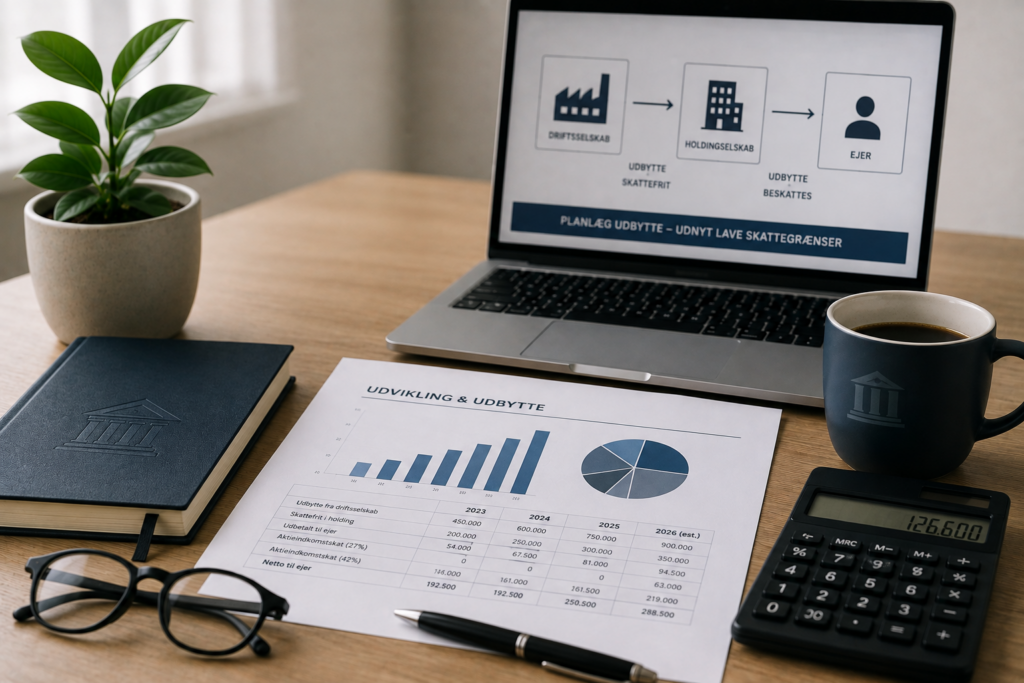
When you run a holding company, dividends are part of everyday life. Money flows from the operating company up to the holding company, and at some point it must go further—either to you as the owner or into new investments. The question is when tax is due and how much. At Accountview, we help owner-managers get a complete overview of taxes on dividends from holding companies, so you can take full advantage of the rules without making any missteps.
As a general rule, dividends paid between companies are tax-exempt
The most important rule regarding the taxation of shares in a holding company is that dividends paid from an operating company to the holding company are tax-free if the holding company owns at least 10 percent of the operating company. This means that you can transfer the profit to the holding company each year without the government taking its share at that stage. Personal income tax only comes into play when the money is paid out to you as an individual.
This offers two key advantages. First, the holding company can serve as a cash reserve for savings and investments while business operations continue. Second, a future distribution to you can be planned to make the best possible use of the low tax thresholds.
How Dividends Are Taxed for You as an Owner
When dividends are paid from the holding company to you as an individual, they are treated as dividend income. The tax consists of two rates. The first 63,300 kroner in 2026 are taxed at 27 percent, while amounts above that are taxed at 42 percent. If you are married, you have two tax-free thresholds, so together you can receive up to 126,600 kroner at the lower rate.
This is exactly where planning pays off. With good timing, the distribution can be spread out over several years so that you qualify for the lower tax rate each year. We’ll help you do the calculations along with your estimated tax return so you know how much you can withdraw without unnecessarily increasing your tax bill.
Tax on the holding company itself
The holding company pays corporate income tax at a rate of 22 percent on its taxable income. In practice, the profit is often low because dividends from the operating company are tax-free. On the other hand, the holding company may have income from equity investments, interest, and investments, which may be fully or partially taxable.
For investments in publicly traded stocks, there are two distinct rules. Stocks in which the holding company owns at least 10 percent are, as a general rule, tax-exempt. Stocks in the portfolio representing less than 10 percent are taxed on an ongoing basis according to the inventory method. We always review your investments and determine the correct tax treatment so that you can avoid errors when filing your tax return.
We handle the holding company's taxes
At Accountview, we ensure that both the operating company and the holding company work in harmony. You’ll be assigned a dedicated advisor who is familiar with your company’s history and can provide a quick assessment whenever dividends, acquisitions, or an exit are on the horizon.
Among other things, we offer:
- Calculation and Reporting of Dividend Tax Each Year
- Assessment of the Optimal Distribution Amount
- Accounting and Annual Report for the Holding Company
- Contacting the Tax Authority Regarding Questions or Audits
- Consulting in Connection with a Generational Transition or Sale
This provides peace of mind, and it means you can focus on your business instead of the fine print. We also conduct a brief annual status meeting where we review the structure and assess whether there are any changes to your plans that should be reflected in your tax strategy.
Frequently Asked Questions
How long do I need to hold the shares before I can receive tax-free dividends between the companies?
The 10 percent threshold must be met, but there is no minimum holding period required to receive the dividends tax-free, as long as the holding company owns at least 10 percent of the operating company. However, special rules apply to the subsequent sale of the shares, where a three-year holding period may be relevant.
Can I pay dividends in the middle of the year, or do I have to wait until after the annual report is released?
Dividends may be paid as ordinary dividends following approval of the annual report or as extraordinary dividends during the year. Extraordinary dividends require an audited interim financial statement and a resolution at the general meeting, and we’ll help with the documentation so that the tax authorities and the bank receive what they need.
What should I do if the dividend is paid in a foreign currency?
Dividends in foreign currency are converted to Danish kroner on the date of approval, and this value forms the basis for taxation. Any exchange rate fluctuations up until the date of payment affect only the company’s income statement. We set up the conversion so that you use the correct basis in your reporting.
Would you like a detailed analysis of your dividend strategy? Let’s have a no-obligation conversation about your holding company.